DOJ sues UnitedHealth over $1B+ in Medicare claims

http://www.beckershospitalreview.com/payer-issues/doj-sues-unitedhealth-over-1-billion-in-medicare-false-claims-again.html

Image result for dept of justice

The Justice Department sued Minnetonka, Minn.-based UnitedHealth Group Tuesday, alleging the payer defrauded Medicare at least $1 billion in false claims.

In the 103-page lawsuit filed in a Los Angeles federal court, the Justice Department alleged the payer knowingly inflated risk adjustment payments by providing the government inaccurate data about the health status of its beneficiaries. Department officials cited UnitedHealth’s “one-sided” chart review process that reportedly didn’t address errors elevating its revenues.

The department also alleges the payer ignored “invalid diagnoses from healthcare providers with financial incentives to furnish such diagnoses.“

The move follows the department’s decision to intervene in a whistle-blower suit filed by James Swoben in 2009. That suit alleges UnitedHealth billed Medicare higher payments for patients by “making patients look sicker than they” were. In an earlier statement to Star Tribune, UnitedHealth spokesperson Matt Burns said the payer denied the claims and has “been transparent with [CMS] about our approach under its unclear policies. We reject these claims and will contest them vigorously.”

This is the second lawsuit the department has filed against the insurer this month. The other lawsuit concerns separate but similar allegations filed under seal in 2011 by Benjamin Poehling, former finance director of UnitedHealthcare Medicare and Retirement.

Are CEOs Less Ethical Than in the Past?

https://www.strategy-business.com/feature/Are-CEOs-Less-Ethical-Than-in-the-Past?gko=50774&utm_source=itw&utm_medium=20170516&utm_campaign=resp

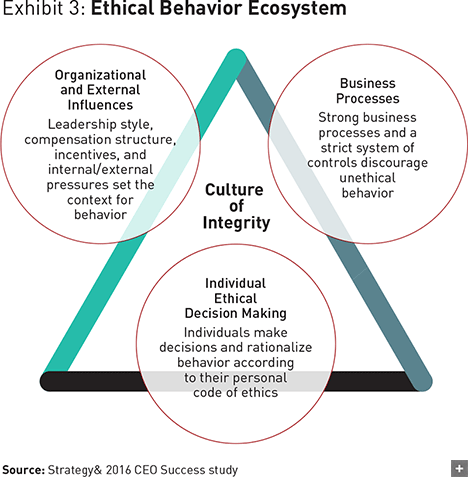
The job of a chief executive officer at a large publicly held company may seem to be quite comfortable — high pay, excellent benefits, elevated social status, and access to private jets. But the comfortable perch is increasingly becoming a hot seat, especially when CEOs and their employees cross red lines.

As this year’s CEO Success study shows, boards of directors, institutional investors, governments, and the media are holding chief executives to a far higher level of accountability for corporate fraud and ethical lapses than they did in the past. Over the last several years, CEOs have often garnered headlines for all the wrong reasons: for misleading regulators and investors; for cutting corners; and for failing to detect, correct, or prevent unethical or illegal conduct in their organization. Some high-profile cases, involving some of the world’s largest corporations, have featured oil companies bribing government officials and banks defrauding customers.

To be sure, the number of CEOs who are forced from office for ethical lapses remains quite small: There were only 18 such cases at the world’s 2,500 largest public companies in 2016. But firings for ethical lapses have been rising as a percentage of all CEO successions. (We define dismissals for ethical lapses as the removal of the CEO as the result of a scandal or improper conduct by the CEO or other employees; examples include fraud, bribery, insider trading, environmental disasters, inflated resumes, and sexual indiscretions. See “Methodology,” below.) Globally, dismissals for ethical lapses rose from 3.9 percent of all successions in 2007–11 to 5.3 percent in 2012–16, a 36 percent increase. The increase was more dramatic in North America and Western Europe. In our sample of successions at the largest companies there (those in the top quartile by market capitalization globally), dismissals for ethical lapses rose from 4.6 percent of all successions in 2007–11 to 7.8 percent in 2012–16, a 68 percent increase.

http://www.beckershospitalreview.com/hospital-management-administration/ceo-turnover-for-misbehavior-up-36-worldwide.html


Dignity Health reports $85M operating loss in Q3

http://www.beckershospitalreview.com/finance/dignity-health-reports-85m-operating-loss-in-q3.html

Image result for dignity

San Francisco-based Dignity Health saw a decrease in revenue in the third quarter of fiscal year 2017, according to an unaudited quarterly report.

The nonprofit health system reported revenues of $3.14 billion for the three-month period ended March 31, down about 2 percent from $3.2 billion in the same period the year prior. Dignity partially attributed lower revenues to a $111.3 million decrease in net patient and premium revenue over the same period in the previous fiscal year.

The system’s operating loss more than doubled in the third quarter when compared with the same period last year. For the three-month period, the health system recorded operating losses of $85.4 million, up from $41.7 million in the same period the year prior.

Dignity attributed the loss to several factors, including unrecognized provider fee income during the period, which is pending CMS approval. The system recorded provider fee income of $108.9 million in the third quarter of the previous fiscal year.

For the nine months ended March 31, Dignity reported an operating gain of $79.5 million, up from an operating loss of $87.1 million for the same period in the prior year.

Moody’s: US nonprofit hospitals see decrease in median operating margin

http://www.beckershospitalreview.com/finance/moody-s-us-nonprofit-hospitals-see-decline-in-median-operating-margin.html

OR Efficiencies

U.S. nonprofit hospitals’ median operating margin fell in fiscal year 2016 as expenses grew, according to preliminary financial data compiled by Moody’s Investors Service.

The data is from the agency’s annual report, “Not-for-profit Healthcare and Public Hospitals — US: Preliminary 2016 Medians Skew Lower As Revenue and Expense Pressures Hinder Profitability.” For the report, Moody’s examined audited fiscal year 2016 financial statements for 150 hospitals and health systems.

Here are seven things to know from the analysis.


Kaiser raises record $4.4 billion in white-hot hospital bond market

http://www.modernhealthcare.com/article/20170510/NEWS/170519985

Image result for white-hot hospital bond market

Kaiser Permanente raised $4.4 billion through a series of three bond offerings this month.

That’s a record for the Oakland, Calif.-based health plan and hospital giant, which plans to use the proceeds to fuel expansion, said Chief Financial Officer Kathy Lancaster.

The aggregate interest rate on the A+-rated bonds was a stellar 3.8%.

Kaiser Permanente investors ordered four to five times as many of the A+-rated bonds as were available, Kaiser Treasurer Tom Meier said. Overall, the bond market is white-hot for hospital debt offerings.

Just this month, Community Health Systems grew a $700 million debt offering to $900 million. Competition for MetroHealth’s $945.7 million offering dropped the rate to under 5%.

MetroHealth, located just west of Cleveland, raised the money to finance the transformation of its main campus, including a new replacement hospital. Struggling CHS is refinancing debt that was expiring.

Corporate bond activity is expected to remain robust, even if the Federal Reserve raises interest rates a couple of quarter-point notches this year, according to an April debt report by Fitch Ratings.

Even with a quarter-point increase in March, Fed borrowing rates are still near a historic low at 1%. The government will only continue to raise interest rates if the economy is strong, said Fitch Managing Director Megan Neuburger.

What that means for hospitals is that higher interest rates would be offset by more patient volume since consumers might feel more financially comfortable getting elective and preventive care.

That’s the case even for troubled systems such as CHS with below-investment-grade debt ratings.

“The high-yield (bond) market is healthy,” Neuburger said.

Kaiser, the nation’s largest integrated health system with annual revenue of $71 billion, needs more hospital capacity, physician offices and technology enhancements after adding about 2.5 million new health plan members over the past three years, Lancaster said.

The recent acquisition of Group Health in Seattle and other organic growth has brought Kaiser’s enrollment to 11.7 million members.

Most of those enrollees will get their care at Kaiser’s 39 hospitals and hundreds of medical offices staffed by Permanente physicians contracted to Kaiser.

For Kaiser to meet its mission of convenient, affordable care, the system needs to keep investing in locations and technology that allows patients to select whether they come to a physician office or connect with its physicians through telemedicine or secure internet links, CEO Bernard Tyson told a Nashville Health Care Council luncheon audience last month.

Part of the reason this month’s offering was so big is that Kaiser had not gone to the debt markets since 2012, Lancaster said. Typically, it would do an offering every other year. But the need for capital and low interest rates urged Kaiser to put together the offering, Lancaster said.

Kaiser likes to operate with a debt-to-capitalization ratio of 20% to 30%, she said. The recent offering puts the system at 28%.

Interestingly, $1 billion of the $4.4 billion in bonds were designated as “green bonds” or those that appeal to funds and investors that look for environmentally or socially friendly organizations to invest in, Lancaster said.

Kaiser received that designation due to its new environmentally friendly hospital in San Diego that opened two weeks ago, she said.

MetroHealth reports that it had 122 banks, funds, firms and individuals put in orders for its hospital bonds.

“Not only is this an important validation of the success we’ve earned with our strategy, recent growth and operating performance improvements, it’s proof of the industry’s belief in MetroHealth and the path we’re taking,” said Dr. Akram Boutros, MetroHealth CEO.

The health system is using the proceeds to construct a new 12-story, 270-bed replacement hospital on its main campus as well as a new central utility plant and parking garage among other projects.


Kaiser hits $1 billion operating gain in Q1

http://www.modernhealthcare.com/article/20170515/NEWS/170519892?utm_campaign=CHL:%20Daily%20Edition&utm_source=hs_email&utm_medium=email&utm_content=51986490&_hsenc=p2ANqtz-839Ex2h99Z8rm5tf8l2lPojAGaBIqcTZ4WSv6wsJY2cbOYWcNtHo6UgIzmQJnqy-2QzLnCsclP8jXne8igI2EeUoSRaA&_hsmi=51986490

Image result for kaiser permanente thrive

Kaiser Permanente Monday posted a record $1 billion operating gain in its first quarter, just days after holding its largest-ever bond offering.

The Oakland, Calif.-based health plan and hospital giant eclipsed the $1 billion barrier on revenue of $18.1 billion. That compared with an operating gain of $701 million on revenue of $16.3 billion in the year-earlier quarter.

The 5.5% operating margin in the first quarter beat the strong 4.3% operating margin from the year-earlier period.

Not-for-profit Kaiser is the nation’s largest integrated health system with 11.7 million health plan members and 39 hospitals.

Its record first quarter was disclosed in a financial filing Monday.

Efforts to reach Kaiser for a comment late Monday were unsuccessful.

Kaiser’s performance was only nominally aided by contributions from its $1.8 billion acquisition of Seattle-based Group Health Cooperative on Feb. 1.

Group Health contributed $18 million of operating income on revenue of $709 million over the last two months of the quarter, the financial filing shows.

Kaiser earlier this month raised a record $4.4 billion through a series of three bond offerings to build out access points in its current markets and look for growth opportunities in communities neighboring its facilities. Those include hundreds of physician offices and outpatient centers across the country.

Kaiser reported operating income of $1.9 billion on revenue of $64.6 billion in full-year 2016 compared with operating income of $1.8 billion on revenue of $60.7 billion in the prior year.

In the first quarter of 2017, Kaiser also posted an investment gain of $582 million compared with an investment loss of $157 million in the year-ago period.

The operating gain coupled with the investment gain and other non-operating income pushed Kaiser to a net gain in the quarter of $1.56 billion.

Kaiser only books actual investment gains, not paper or unrealized gains in its investment portfolio.

The right place for the right care

http://www.us.jll.com/united-states/en-us/Research/US-Healthcare-Perspective-2017-JLL.pdf?661ac41b-8177-4716-8c89-a88e24e95f17

Image result for healthcare real estate strategy

How can we improve the health of our communities, while also reducing costs and maintaining high-quality care? And how will we pay for it? These are the most vexing questions facing healthcare executives today.

An expanded patient base will be necessary for survival. Location is an increasingly critical factor in determining future success, with many asking: “Where do we need to be and what kind of service do we need to deliver?”

Uncertainty is unavoidable in the healthcare industry. But regardless of what direction healthcare reform may take, certain facts will not change. Healthcare costs must decrease to provide more care to more people, and keeping patients out of expensive hospital settings can drive down the cost of care and simultaneously improve population health. The right real estate strategy can help hospitals ensure that they have the right places for the right care.